 Founder Data Report
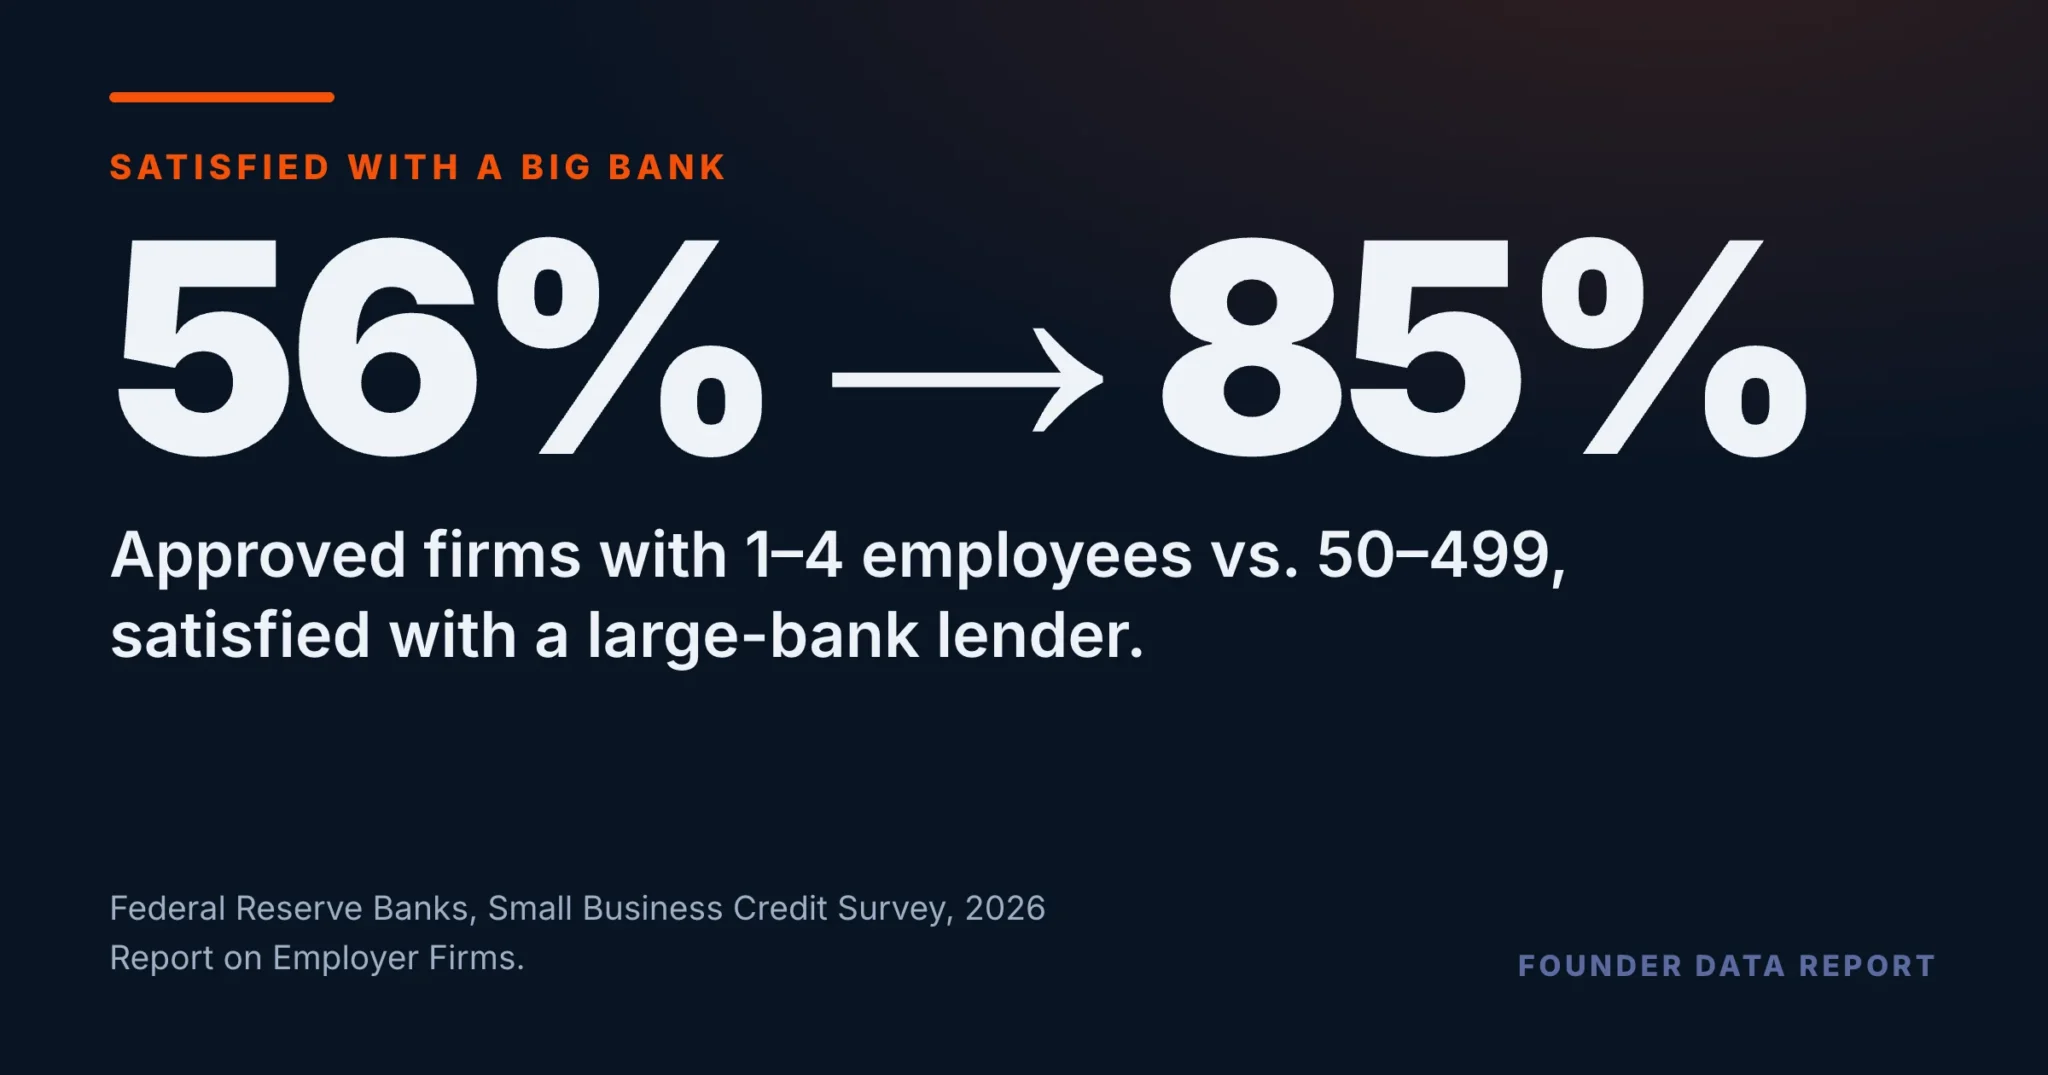
At Big Banks, 85% of Approved Firms With 50 to 499 Employees Were Satisfied. With 1 to 4 Employees, 56%.
Get clarity — download the free Entrepreneur Survival Guide Summary.
The Federal Reserve asked approved borrowers how they felt about their lender afterward. At big banks, the answer depends on how big the borrower is.
In the Federal Reserve’s 2025 Small Business Credit Survey, 85% of firms with 50 to 499 employees that were approved at a large bank said they were satisfied with that lender. Among approved firms with 1 to 4 employees, 56% were. Applicants with 50 to 499 employees were also about twice as likely to report no problems at all with a large bank (73% against 38%). Online lenders sit lower overall: 35% of approved borrowers were satisfied, and 61% of applicants named a high interest rate as a problem.
- The Fed asked firms approved for a loan, line of credit or cash advance how satisfied they were with the lender.
- At large banks: 56% satisfied with 1–4 employees, 85% with 50–499. The gap clears both confidence intervals.
- Large-bank applicants reporting no problems: 38% at 1–4 employees, 73% at 50–499.
- The sizes in between cannot be cleanly separated from the ends.
- Across all sizes, small and large banks satisfy about two in three approved borrowers. Online lenders, 35%.
Same bank type, different experience
The Small Business Credit Survey asks firms that were at least partly approved for a loan, line of credit or merchant cash advance how satisfied they were with the lender. At large banks the answer moves with the size of the borrower. 56% of approved firms with 1 to 4 employees were satisfied, and 60% with 5 to 9. With 10 to 19 and 20 to 49 employees it was 74% and 76%, and with 50 to 499 it was 85%. The Fed publishes a 95% confidence interval for each figure. Only the gap between the largest group and the smallest clears them; the groups in between overlap one end or both. Most of the smallest firms that were not satisfied were not unhappy either: 37% called themselves neutral and 8% dissatisfied.
Share of firms at least partly approved for a loan, line of credit or merchant cash advance at a large bank who said they were satisfied with it. Slate and orange mark the two ends, whose 95% confidence intervals do not overlap; amber marks groups whose intervals overlap one end or both.
Federal Reserve Banks, Small Business Credit Survey, 2026 Report on Employer Firms and its data appendix (sbcs-employer-firms-appendix-2025.xlsx). Survey fielded September 3 to November 14, 2025; employer firms with 1–499 employees. Retrieved from fedsmallbusiness.org on October 10, 2026.
The bank is the same kind of bank. The experience of it is not.
Fewer problems on the way in
The same pattern shows up before the decision. The survey asks every applicant at a lender which problems they ran into there, and lets them pick several or none. At large banks, 38% of applicants with 1 to 4 employees and 36% with 5 to 9 said they had no problems. With 50 to 499 employees, 73% did. Among the smallest applicants, 29% said the criteria for approval were unclear, against 13% of applicants with 10 to 19 employees. The other size groups overlap on that answer.
Share of applicants for a loan, line of credit or merchant cash advance at a large bank who chose “experienced no challenges.” Slate marks the two smallest groups, whose 95% confidence intervals sit wholly below the 50–499 group (orange); amber marks groups whose intervals overlap both.
Federal Reserve Banks, Small Business Credit Survey, 2026 Report on Employer Firms and its data appendix (sbcs-employer-firms-appendix-2025.xlsx). Survey fielded September 3 to November 14, 2025; employer firms with 1–499 employees. Retrieved from fedsmallbusiness.org on October 10, 2026.
Where online lenders sit
Across firms of every size, approved borrowers were satisfied with small banks (65%) and large banks (64%) at about the same rate, and with finance companies at 57%. Online lenders sit clearly below both kinds of bank at 35%; finance companies, with a wider interval, overlap both the banks and the online lenders. Most of the rest were neutral (51%) rather than dissatisfied (15%). The complaint is price: 61% of online-lender applicants named a high interest rate, against 28% at large banks and 30% at small banks. By size, online-lender satisfaction runs between 26% and 36% from 1 to 49 employees, and those groups cannot be told apart. The Fed does not publish the 50 to 499 figure for online lenders. For the smallest firms, small banks (59%) and large banks (56%) are level.
Share of firms at least partly approved at each type of lender who said they were satisfied with it. Lender types with fewer than 250 responding firms are left out. Online lenders’ 95% confidence interval (slate) sits wholly below both banks’; finance companies (amber) overlap both groups.
Federal Reserve Banks, Small Business Credit Survey, 2026 Report on Employer Firms and its data appendix (sbcs-employer-firms-appendix-2025.xlsx). Survey fielded September 3 to November 14, 2025; employer firms with 1–499 employees. Retrieved from fedsmallbusiness.org on October 10, 2026.
What to take from this if you are building a company
Treat a lender as a relationship you are entering, not a rate you are accepting. The smallest borrowers in this survey were less likely than the largest to come away satisfied from a large bank, and more likely than firms of 10 to 19 to say the rules were unclear, so ask the questions the survey points at before you sign: what decides approval, how long the decision takes, and what the full cost is. Online lenders drew fewer complaints about waiting (8% named a long wait, against 21% at large banks) and far more about the rate, and about two in three approved online borrowers did not call themselves satisfied. Whichever you choose, keep a second lender relationship warm before you need it. Trust is easier to judge when you are not waiting on a yes.
Four limits worth holding. The survey is a convenience sample, not a random one; the Federal Reserve weights it to match the population of employer firms with 1–499 employees. Satisfaction was asked only of firms that were at least partly approved, so it says nothing about firms that were turned down. The size groups are small at each lender (76 to 172 approved firms at large banks), so only gaps whose 95% confidence intervals do not overlap are reported as differences. And the survey records how firms felt, not the terms they got or why.
Federal Reserve Banks, Small Business Credit Survey, 2026 Report on Employer Firms.
Frequently Asked Questions
How satisfied are small businesses with their lenders?
Among firms at least partly approved in the Fed's 2025 survey: 65% were satisfied with small banks, 64% with large banks, 57% with finance companies and 35% with online lenders.
Does company size change how firms feel about large banks?
At the ends, yes. 56% of approved firms with 1–4 employees were satisfied with a large bank, against 85% with 50–499. The groups in between overlap one end or both.
What problems do small firms report at large banks?
Among applicants with 1–4 employees: high interest rate (30%), unclear approval criteria (29%) and a difficult application (24%). Firms could name several. 38% named none.
Why are online lenders rated lower?
The survey does not ask why, but 61% of online-lender applicants named a high interest rate as a problem, against 28% at large banks. Most online borrowers who were not satisfied called themselves neutral.
Is the Small Business Credit Survey representative?
It is a convenience sample of employer firms with 1–499 employees, weighted by the Federal Reserve to match that population by size, age, industry, geography and owner demographics.
Published by The Lonely Entrepreneur — the community and coaching platform for entrepreneurs who are building alone. lonelyentrepreneur.com
This article is for educational purposes and is not a substitute for professional financial or legal advice.